Key Takeaways
- Define how you plan to use your 30A second home, whether for vacations, retirement, rental income, or long-term ownership.
- Compare communities based on beach access, traffic, parking, nearby services, and everyday convenience.
- Review flood exposure, elevation, storm protection, and previous property damage before making an offer.
- Calculate the full cost of ownership, including insurance, taxes, utilities, maintenance, and emergency repair reserves.
- Verify short-term rental regulations, HOA restrictions, and association requirements before relying on rental income.
- Compare single-family homes, condos, and townhomes based on maintenance responsibilities, fees, and available amenities.
- Examine association finances, reserves, pending assessments, and planned repairs when considering a shared-property community.
- Use a consistent scorecard to evaluate location, condition, affordability, rental potential, and resale considerations.
Buying a second home along Florida’s 30A can be exciting, whether you picture quiet mornings near the dunes, family beach trips, or a place to use during retirement. Before making an offer, however, look beyond the view and asking price. Buyers comparing communities from Rosemary Beach and Seacrest to Santa Rosa Beach and WaterColor can benefit from local guidance from 30A real estate agents at The Gettings Group, a team serving 30A, South Walton, Destin, and the Emerald Coast with home-search resources, neighborhood insights, and buyer support. A coastal home should work for your lifestyle, budget, and long-term plan. Insurance availability, flood exposure, building condition, association rules, rental limitations, and travel convenience can all affect the real cost and enjoyment of ownership. A careful review early in the process can prevent a beautiful property from becoming an expensive surprise.
Start With the Property’s Main Purpose
Define how you expect to use the home before comparing listings. The right property for a private family retreat may not be the right property for frequent guests or rental use.
- Personal vacations: Prioritize bedroom count, storage, parking, outdoor living space, and proximity to the beach access your family will actually use.
- Part-time retirement: Consider grocery access, medical services, stairs, walkability, and how the home feels outside peak vacation periods.
- Rental use: Focus on permitted rental activity, guest appeal, durable finishes, cleaning logistics, and realistic operating costs.
- Long-term ownership: Look for a location and property type that will continue to appeal to future buyers, not only to your current preferences.
Many buyers want a combination of personal enjoyment and rental income. That can work, but it requires a realistic plan for blocked owner dates, management, upkeep, furnishing, and seasonal demand.
Review the Location Beyond the Beach
On 30A, a home’s position can shape daily life as much as its distance from the Gulf. Visit the area at different times, including on a busy weekend, to understand traffic patterns, parking, pedestrian activity, and neighborhood noise.
- Measure the actual walk or bike ride to public beach access, not simply the distance shown on a map.
- Check access to groceries, restaurants, parks, trails, medical care, and Northwest Florida Beaches International Airport.
- Look at road access during holiday periods and summer travel season.
- Ask about nearby construction, planned development, drainage work, or road projects.
- Consider whether the property has practical parking for family members, guests, and service providers.
A home a few blocks inland may offer easier year-round access, more parking, and a different ownership-cost profile than a comparable Gulf-front property. The best location is the one that matches how you will use the home, rather than the one with the shortest possible walk to the sand.
Check Flood, Storm, and Elevation Factors Early
Do not wait until the final days of due diligence to investigate risk. Start with the property address and review the official flood mapping tools available for the community, then discuss the findings with an insurance professional and qualified local inspectors. Map designations are useful, but they are only one part of a complete property review.
- Ask for the current flood-zone designation and any available elevation documentation.
- Request disclosure information and permits related to prior water, wind, mold, roof, or structural repairs.
- Confirm the roof age, roof material, and condition of exterior finishes.
- Inspect windows, exterior doors, drainage paths, decks, railings, and retaining features.
- Ask about storm shutters, impact protection, generators, and evacuation planning.
- Verify that major repairs were properly permitted and completed by qualified contractors.
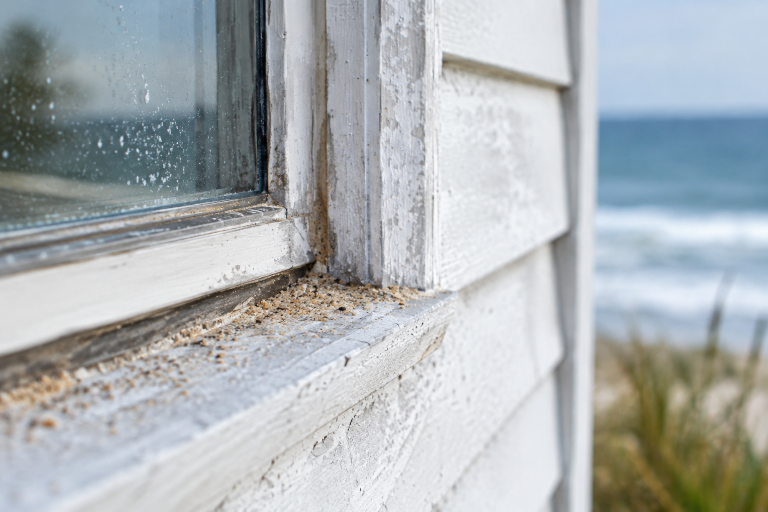
Salt air, wind-driven rain, humidity, and heavy use can place added demands on a coastal property. An inspection should focus on the systems and materials most exposed to those conditions, including the roof, HVAC equipment, plumbing, exterior paint, seals, and outdoor structures.
Build a Full Coastal Ownership Budget
The purchase price is only the starting point. Create a normal-year budget and a high-cost-year budget that includes a major repair, a deductible, an insurance change, or a period without rental income. This approach gives you a more durable view of affordability.
- Mortgage principal, interest, and property taxes.
- Homeowners, windstorm, flood, and liability coverage, as applicable.
- Utilities, internet, security monitoring, pest control, and trash service.
- HOA or condominium fees.
- Pool care, landscaping, cleaning, and routine maintenance.
- Storm preparation, repair reserves, and replacement of furnishings or appliances.
- Property-management, booking, and turnover costs if the home will be rented.
Insurance deserves special attention. Policy terms, deductibles, eligibility standards, and coverages vary by insurer and property, so review Florida homeowners insurance requirements and consumer information before assuming a prior owner’s costs will apply to you.
Understand Rental Rules Before Counting Income
Being close to the beach does not automatically make a home a profitable rental. Local government requirements, community documents, minimum-stay rules, parking limits, and association restrictions can all affect whether and how a property may be rented.
- Confirm city, county, and neighborhood rules that apply to short-term rentals.
- Read HOA or condominium documents for rental limits, registration requirements, and guest rules.
- Estimate income conservatively across the full year, not only during the busiest weeks.
- Subtract cleaning, management, platform, maintenance, furnishing, tax, and repair costs before judging performance.
Gross rental revenue is not profit. Buyers should review projections with a tax professional and make sure the home still fits their budget if rental income is lower than expected.
Compare Property Types and Community Finances
Single-Family Homes
Detached homes can provide privacy, storage, outdoor space, and more control over improvements. They may also require more direct responsibility for exterior maintenance, landscaping, pools, roofs, and storm preparation.
Condos, Townhomes, and Planned Communities
These properties can simplify some maintenance and may include shared amenities. In exchange, owners should closely examine association fees, rules, insurance arrangements, reserves, special assessments, meeting minutes, and planned capital projects. A low monthly fee is not automatically a benefit if needed maintenance has been postponed.
Use a Simple Scorecard Before Making an Offer
Score each contender from one to five in the following categories. The exercise helps separate a strong long-term choice from a property that creates a powerful first impression.
- Location: Access, convenience, privacy, parking, and future buyer appeal.
- Condition: Roof, structure, systems, maintenance needs, and storm readiness.
- Cost: Complete annual ownership budget and emergency reserve needs.
- Rules: Rental, parking, pet, occupancy, and association restrictions.
- Income potential: Conservative rental performance after expenses, if rentals matter.
- Resale: Property type, neighborhood demand, usable layout, and overall condition.
Final Questions to Ask During Due Diligence
Before removing contingencies, ask how old the roof is, whether the property has prior storm or water damage, what insurance options are available, which repairs may be needed within five years, and whether the furniture is included. For association properties, also ask about pending assessments, litigation, reserves, and major planned work. Buying a coastal vacation home on Florida’s 30A should be both an emotional and practical decision. The strongest choice is not always the closest home to the water. It is the property that supports your intended lifestyle, remains manageable in a high-cost year, and gives you confidence in its condition, rules, and long-term fit.
Conclusion
Buying a second home along Florida’s 30A requires more than finding a beautiful property near the beach. Buyers should consider how each location supports their intended lifestyle while carefully evaluating insurance availability, flood exposure, maintenance needs, rental restrictions, and the complete cost of ownership. Comparing property types, reviewing community rules, and completing thorough due diligence can help prevent unexpected expenses and ownership challenges. Working with local real estate professionals like The Gettings Group can also provide valuable guidance when exploring communities throughout 30A, South Walton, and the Emerald Coast. Ultimately, the right second home balances personal enjoyment, financial comfort, and long-term practicality while continuing to meet your needs beyond the initial excitement of the purchase.